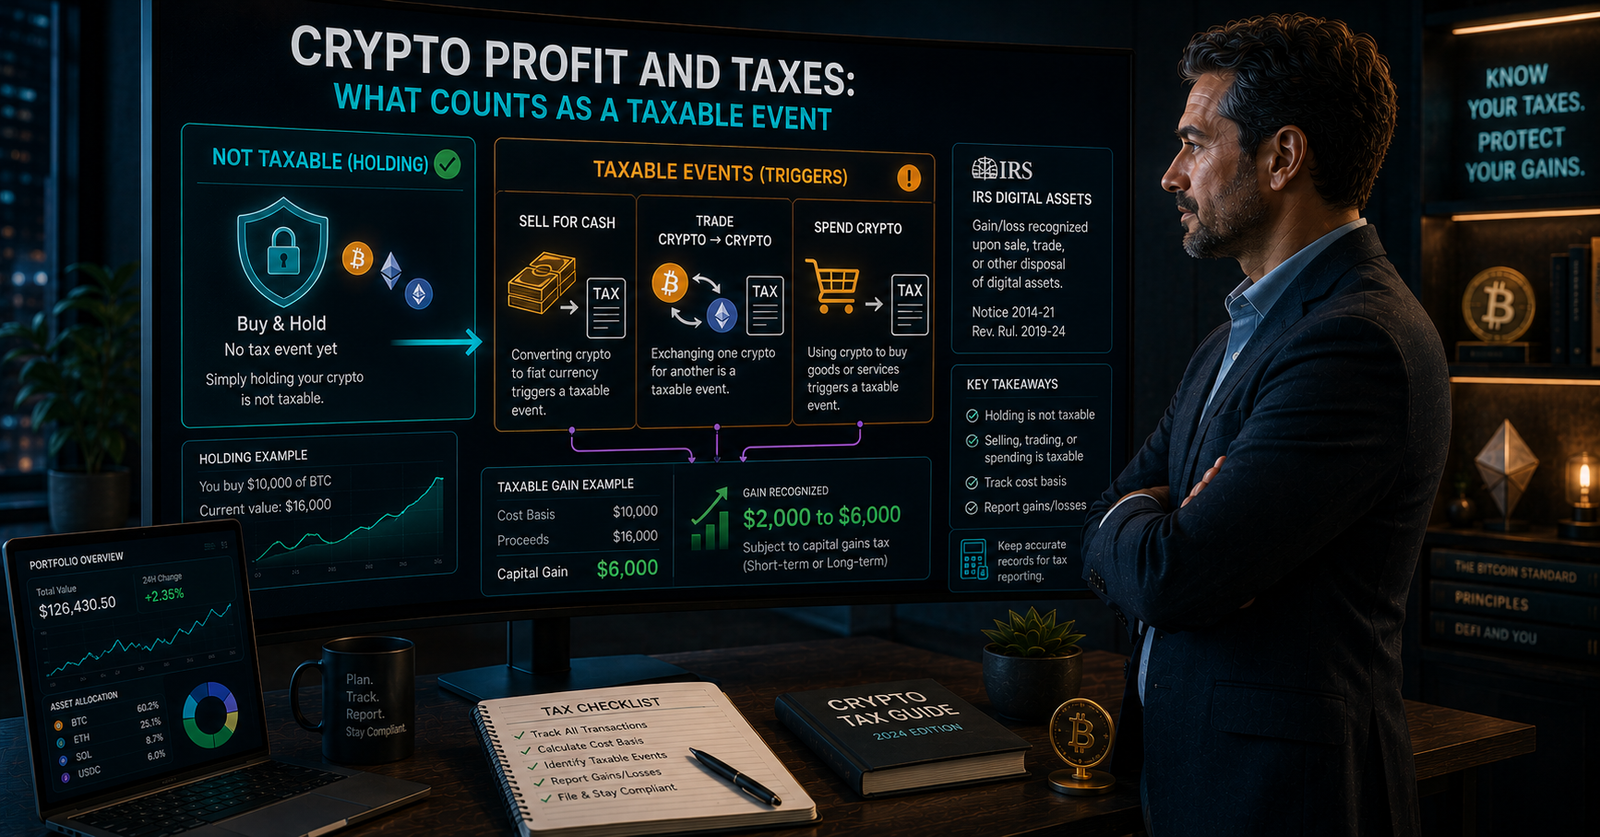
Understanding what counts as a crypto taxable event keeps you from missing something you owe, or worrying about something you don’t.
What Triggers a Taxable Event vs What Doesn’t
Not every crypto action has tax consequences. According to the IRS’s guidance on digital assets, simply buying crypto with cash and holding it isn’t a taxable event on its own. A gain or loss is only recognized once you sell, trade, spend, or otherwise dispose of the asset. Holding, no matter how much the value moves, stays untaxed until you act on it.
| Action | Taxable Event? |
|---|---|
| Buying crypto with cash | No |
| Holding crypto as price rises | No |
| Selling crypto for cash | Yes |
| Trading crypto for crypto | Yes |
| Spending crypto on a purchase | Yes |
| Earning crypto (staking, mining, pay) | Yes, as income |
How to Identify Common Taxable Events
Once you understand the “dispose of the asset” rule, most scenarios become easier to sort into taxable or not.
Selling and Crypto-to-Crypto Trades
Selling crypto for cash is a taxable event. So is trading one coin for another, since the IRS treats that trade as disposing of the first asset, even though no cash ever touched your bank account.
Spending Crypto and Earning Crypto
Using crypto to buy goods or services is also a taxable event, based on the coin’s value at the time of the purchase. Earning crypto through staking, mining, or as payment is generally treated as taxable income when received.
Your P&L; for tax purposes is calculated at the moment of each disposal, using the coin’s value at that exact time, not its value today or at year-end.
A Practical Example of Identifying a Taxable Event
Picture holding a coin that grew from $2,000 to $6,000. If you simply continue holding it, there’s no taxable event yet. But if you trade that coin for a different one, spend part of it on a purchase, or sell it for cash, each of those actions separately triggers a taxable event based on the gain up to that point. This is a clear example of why does trading one crypto for another count as a taxable event is one of the most common points of confusion, since no cash changes hands but the IRS still treats it as a disposal.
Misclassifying a crypto-to-crypto trade as non-taxable is a common mistake. Keep records of every disposal, including trades, so your reported gains match what the IRS expects to see.
Use our free Crypto Profit Calculator to calculate your gain or loss at the moment each taxable event happens — no login needed.
Conclusion
Knowing what counts as a crypto taxable event comes down to one rule: holding isn’t taxed, but disposing of an asset through a sale, trade, or purchase generally is. Keeping track of each transaction as it happens makes tax season far less stressful than trying to reconstruct a year of activity afterward. Calculate your gain or loss at each step so your records stay accurate.
Comments
No comments yet. Be the first to share your thoughts.
Leave a comment